Roof Insurance Claims Derby | Free Drone Survey
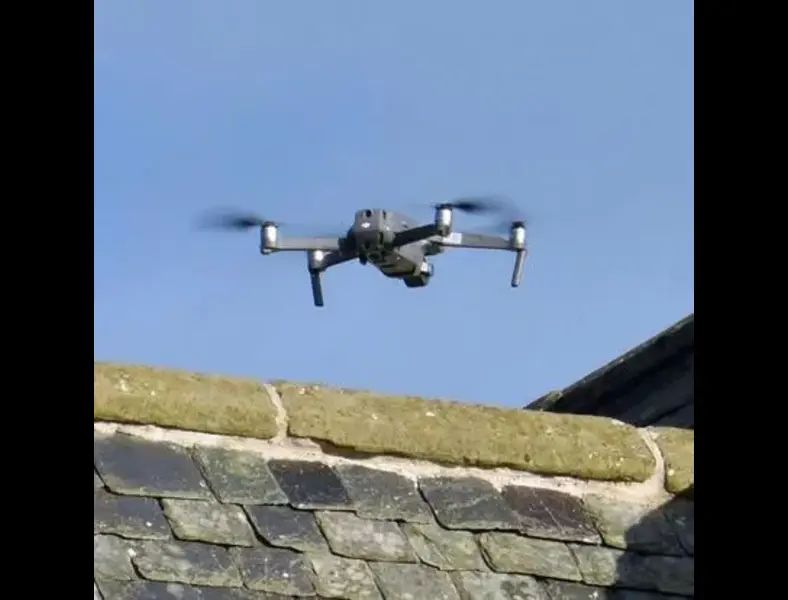
If a storm has torn tiles from your roof or left water coming through the ceiling, the report you get in the first few days often decides whether your insurance claim is paid in full, reduced, or refused. Derby Roofers puts a written, insurer-ready inspection in your hands early, including a free drone survey, so your claim starts with proper evidence rather than a phone description of the damage down the line.
If you would rather talk it through before booking anything, you can reach us through our contact page as well as by phone, and we will tell you honestly whether what you are looking at is likely to be covered.
At a Glance
- Free drone survey producing date-stamped evidence for your insurer
- IPAF and PASMA certified team, so inspections aren’t limited to ground level or drone-only views
- Over 20 years documenting storm and roof damage claims across Derbyshire
Derby Roofers
Roof Insurance Claim Advice
Call us now book a FREE consultation and FREE Quotation
FREE Drone Survey Available
Call: 01332-529704
Roof Insurance Claims in Derby — Get the Settlement You’re Entitled To
We Are Your Trusted, Local Roofing Contractor Serving Derby & Derbyshire
Don’t wait — contact Derby Roofers today for a FREE quote and a FREE drone roof survey.
📞
Call Now: 01332-529704
Has a storm, fallen tree, or sudden leak damaged your roof? You need to act quickly — and you need the right evidence from day one.
At Derby Roofers, we support homeowners across
Derby and Derbyshire through every stage of the roof insurance claims process. We carry out professional roof inspections, produce written damage reports, and
can attend your property when the insurance adjuster visits — so nothing gets missed.
We are available 24 hours a day, 7 days a week. When you call, someone answers. With over 20 years of experience as qualified roofing contractors right here in Derbyshire, we know exactly what insurers look for — and how to document damage in a way that supports a successful claim.
👉 Call us now on 01332-529704 or complete our online form for a FREE drone survey and no-obligation inspection
What Does Buildings Insurance Cover for Roof Damage in Derby?
Homeowners across Derby contact us after storm damage with the same urgent question:
will my insurance pay for this?
Buildings insurance covers the structure of your home — and that includes the roof. Whether your claim is approved depends on
what caused the damage and whether your policy lists that event as a covered peril.
✅ What Is Typically Covered
- Storm damage — high winds, heavy rain, hail, and fallen trees
- Fire and lightning strike
- Vandalism or malicious damage
- Accidental impact from a vehicle or falling object
- Fallen debris — chimney pots, branches, or objects carried by wind
- Water ingress following a covered event — such as tiles blown off in a storm
❌ What Is Typically Not Covered
- Gradual wear and tear
- Neglect or lack of maintenance
- Pre-existing damage not declared when you took out your policy
- DIY repairs carried out to a poor standard
- Gradual deterioration of flat roof felt or membranes
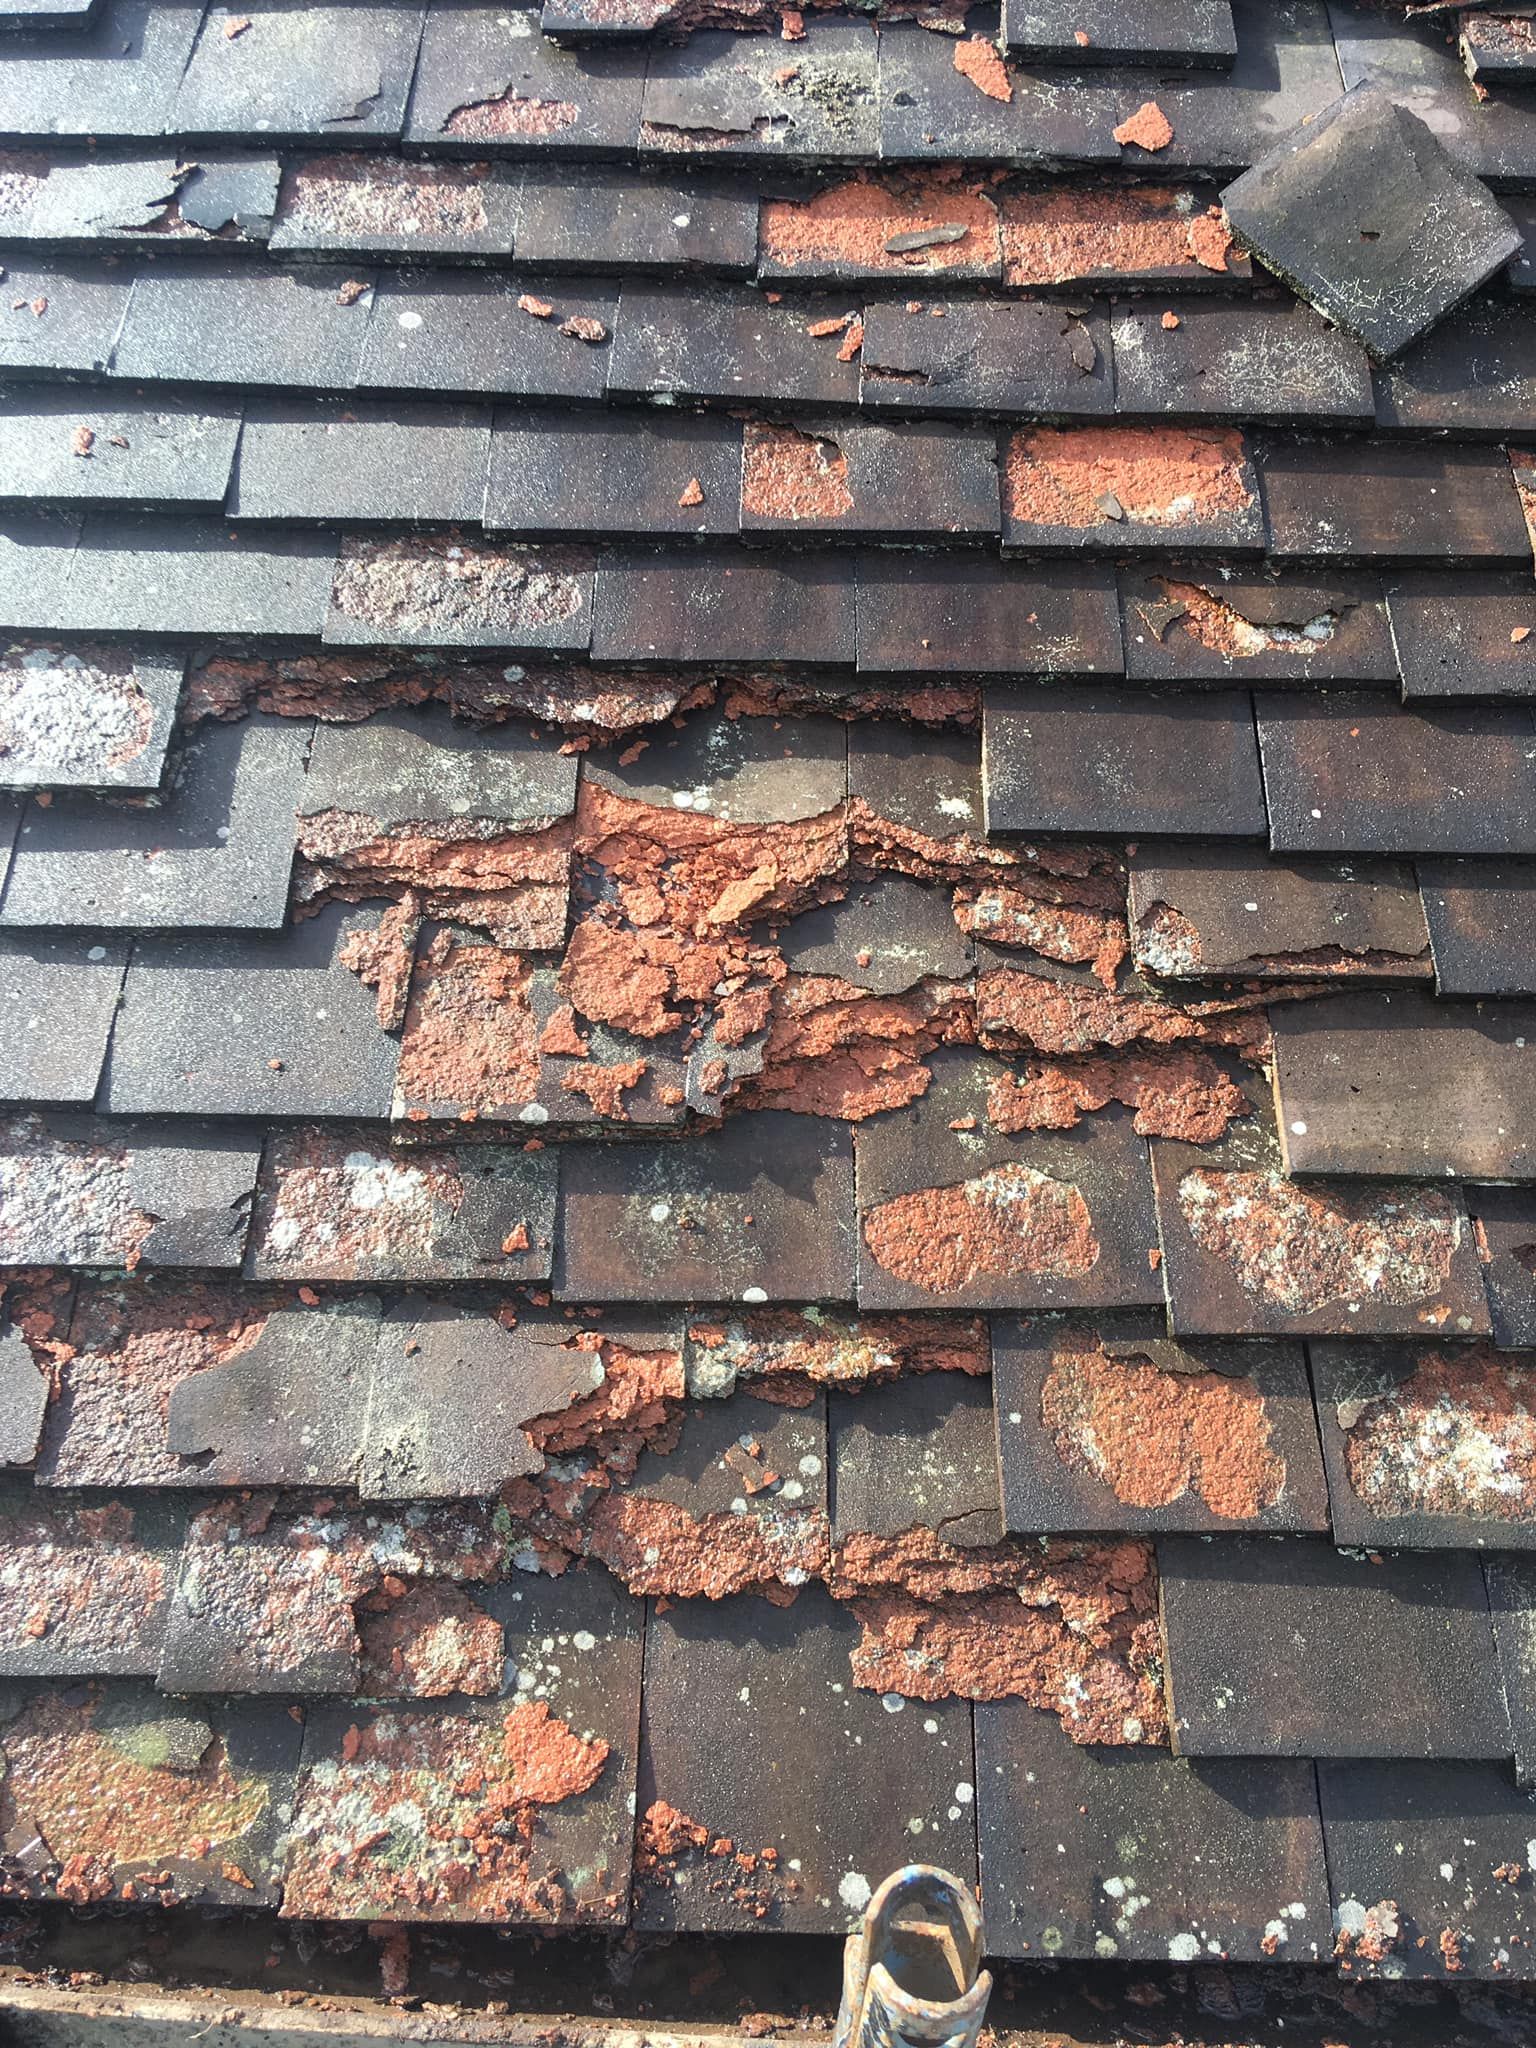
- Moss or lichen damage caused by years of neglect
Derbyshire’s older housing stock — Victorian terraces, clay-tiled roofs, and stone properties — faces particular challenges. Freeze-thaw cycles through winter and strong seasonal winds make roof tile damage common across the county. Your insurer will focus on whether the damage was sudden and unexpected, or developed over time.
One thing many homeowners overlook: if a covered roof leak damages your belongings, your contents insurance may cover those items separately.
Always check both policies when damage occurs.
How to Make a Roof Insurance Claim in Derby — Step by Step
After storm damage, the hours immediately after matter.
Delaying your report to the insurer, or starting permanent repairs before the adjuster has inspected, can reduce or void your payout.
Here is how the process works:
- Stay safe — assess from the ground. Never climb onto a damaged roof. Use binoculars, or call us. We carry out
FREE drone surveys that safely document every area of damage in detail. - Photograph and video everything. Capture the roof, water ingress inside, damp patches, and any damage to ceilings or belongings.
Date-stamp every image. - Arrange emergency temporary repairs if water is getting in. Temporary measures — such as tarping damaged sections — prevent further damage. Keep all receipts.
Many policies reimburse these emergency costs. - Contact your insurer the same day. Most UK policies require prompt notification. Note your claim number and
ask for the adjuster’s direct contact details. - Book a professional roof inspection with Derby Roofers. We carry out a full inspection and produce a written damage report.
This is your most important piece of evidence and can significantly improve your claim outcome. - Get written repair quotes. We provide a detailed, insurer-ready quote. Your insurer may ask for two or three estimates.
- Have your roofer present at the adjuster visit. Ask us to attend when the adjuster inspects your roof. We can point out damage the adjuster might miss and
answer technical questions on the spot — an advantage most Derby homeowners don’t take up. - Submit all documentation together. Photos, our written inspection report, your maintenance history, and repair quotes should be submitted as a complete pack.
⚠️ Important: Most UK insurers require you to report damage within a set timeframe —
often 30 days from discovery. Check your policy wording and do not delay.
How Storm Damage Is Assessed — and What UK Insurers Look For
After a storm hits a property in Derby, many homeowners assume the damage is clearly covered. But insurers look very closely at the cause before approving any payout.
The Association of British Insurers (ABI) defines storm conditions as typically involving gusts of at least
55mph, rainfall of at least
25mm per hour, or hail intense enough to damage hard surfaces.
Derbyshire regularly records gusts above this threshold during named autumn and winter storms — and local Met Office weather data for the date of the event can support your claim directly.
What an Insurance Adjuster Checks
- Whether a
qualifying weather event occurred near your property on the date of the damage - Whether the
damage pattern is consistent with storm impact — not gradual decay - The
condition of the roof before the event — tiles, lead flashing, ridge pointing, and gutters - Any signs of
pre-existing problems that could give the insurer grounds to reduce or refuse the payout
A professional roofer’s written report identifying storm as the primary cause of damage is your strongest piece of evidence. If we carry out your inspection, we document findings clearly, using the correct technical language insurers and adjusters expect.
Note on pre-existing damage: If your roof had visible problems — slipping slates, cracked mortar, or known leaks — before the storm, your insurer may argue those issues contributed to the outcome.
This is exactly why regular maintenance records matter so much.
Why Wear, Tear, and Maintenance History Can Make or Break Your Claim
Many roof insurance claims in Derby are not rejected because of the storm.
They are rejected because of the roof’s condition before the storm arrived.
Insurers expect homeowners to take reasonable care of their property. If your roof shows clear signs of neglect, your insurer can argue the damage was preventable. At that point,
even genuine storm damage may not be fully paid.
Common Maintenance Failures That Weaken a Claim
- Missing or broken tiles left unrepaired for months
- Blocked gutters causing water to back up and penetrate the roof
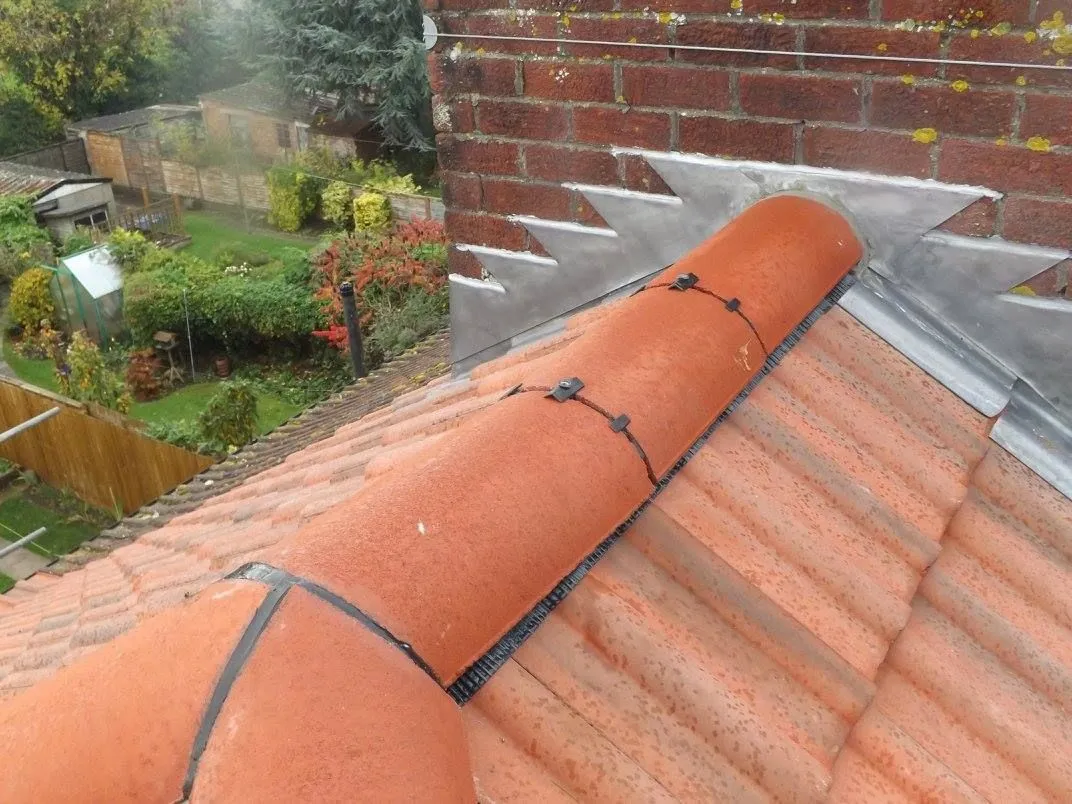
- Failed lead flashing around chimneys or dormers
- Moss or lichen build-up on older clay tile roofs
- Known leaks that were reported but never professionally repaired
- Flat roof felt that has not been inspected or maintained within the last few years
In areas like Spondon, Chaddesden, and Normanton, many homes have clay tile roofs dating back several decades. Insurers look more carefully at older roofs —
a roof over 15 to 20 years old will face closer scrutiny, and the absence of a maintenance record can be used against you.
The good news: a documented history of inspections and professional repairs is strong protection. It shows the insurer that the damage was sudden and unexpected — not the result of years of neglect.
Our recommendation: Book an annual roof inspection with Derby Roofers. We use drone surveys and direct access inspection, and we provide
written reports you can keep on file — ready to support any future claim.
Roof Insurance Claim Rejected in Derby? Here Is What to Do Next
A rejected claim is not necessarily the end.
Most rejections can be challenged — but you need to act in the right order and gather the right evidence.
If your insurer refuses to pay for roof damage in Derby, follow these steps:
- Ask for a written explanation. Your insurer must state the reason and the evidence they relied on. This is your starting point.
- Request a copy of the adjuster’s report. You are entitled to see it.
Check it for errors, assumptions, or gaps. - Commission an independent professional inspection. Derby Roofers can produce a separate written report that identifies the cause of damage and challenges incorrect findings.
- Gather supporting evidence. Local Met Office data for the date of the storm, your maintenance records, and previous inspection reports all strengthen your case.
- File a formal complaint with your insurer. Insurers are legally required to respond to formal complaints within
8 weeks. - Escalate to the Financial Ombudsman Service (FOS). If you are not satisfied with the insurer’s final response, you have
6 months to take your case to the FOS. The FOS examines whether storm conditions occurred near your property, whether the damage matches storm impact, and whether the storm — not wear and tear — was the main cause.
What the FOS expects from insurers: They cannot reject a claim based on assumptions alone. They must provide inspection reports, photographs, or expert assessments to support their decision.
If they cannot produce this evidence, the FOS will weigh your documentation against theirs.
For high-value or complex cases, a public loss assessor can act on your behalf throughout the appeals process. They work directly for you — not the insurer.
Who Is Responsible for Roof Repairs in Flats, Rentals, and Shared Ownership?
Responsibility for roof repairs is not always straightforward. In
Derby city centre and across Derbyshire’s growing number of leasehold and shared-ownership developments, this question comes up regularly.
- Tenants: The roof is part of the building structure. Your landlord’s buildings insurance covers structural damage, including the roof. Your contents insurance covers your belongings.
If a covered roof leak damages your possessions, claim on your contents policy. If your landlord has failed to repair a known roof problem and that failure caused damage, speak to a housing solicitor about your options.
- Leaseholders: Check your lease carefully. In most cases, the freeholder or management company holds the buildings insurance and is responsible for the roof.
You contribute to this through your service charge. Contact the freeholder or managing agent first. - Shared ownership: The housing association typically holds the buildings insurance.
Contact them in writing and keep copies of all correspondence. - Freeholders: You hold the buildings insurance and are fully responsible for the roof. You deal directly with your insurer through the standard claims process.
In all cases: document the damage immediately, report it to the responsible party in writing, and keep a copy of everything sent and received.
Keeping Your Roof Claim-Ready — A Simple Maintenance Checklist
The strongest position to be in when making a roof insurance claim is being able to show your roof was
well maintained before the damage occurred. Many Derby homeowners only think about this after a claim has been turned down.
Here is what we recommend:
- ✅
Inspect your roof at least once a year — ideally in autumn before winter storms arrive, and again in spring after the cold season. Derby Roofers offers professional inspections using drone surveys and direct access methods. - ✅
Clear gutters and downpipes regularly — blocked gutters are one of the most common causes of secondary roof and wall damage across Derbyshire properties.
- ✅
Replace damaged or missing tiles promptly — a single slipped slate, left for months, can allow water into the roof structure and give an insurer grounds to question your maintenance history. - ✅
Check lead flashing around chimneys and dormers — flashing is often one of the first elements to fail on older Derbyshire properties. - ✅
Keep written records of all roofing work — dates, the name of the contractor, and what was done. Even dated photos taken on your mobile phone are useful evidence. - ✅
Tell your insurer about significant changes — solar panel installation, roof lights, loft conversions, or flat roof membrane replacements should be declared. Undeclared structural changes can affect your cover. - ✅
Ask about accidental damage cover —
not all standard policies include this. It can cover events like accidentally stepping through a flat roof during maintenance, or equipment dropped during a DIY project.
Note: If roofing work affects more than
25% of your roof area, building regulations may require notification to Derby City Council. Our team can advise you during any inspection visit.
Frequently Asked Questions — Roof Insurance Claims in Derby
Does home insurance cover roof repairs in Derby?
Yes — if the damage was caused by a sudden, unexpected event listed in your policy, such as storm damage, fire, a fallen tree, or vandalism. It will not cover damage caused by wear and tear, neglect, or gradual deterioration. Always check your policy excess and any conditions relating to roof age or flat roofs before filing a claim.
Does house insurance cover broken roof tiles?
Yes, in most cases — provided the tiles were broken by a sudden event such as a storm or falling debris. If tiles have cracked or slipped due to age and general deterioration, most UK policies will not cover the cost of replacement. The cause of the breakage is the key factor your insurer will examine.
What counts as storm damage for insurance purposes in the UK?
The ABI defines storm conditions as typically involving wind gusts of at least 55mph, rainfall of at least 25mm per hour, or damaging hail. However, insurers and the Financial Ombudsman Service will also consider local weather records, the type of damage, and whether the storm was the primary cause — not just background wear and tear.
How long do I have to report roof damage to my insurer?
Most UK policies require you to report damage promptly — typically within 30 days of discovery. Check your own policy wording for the exact timeframe. Reporting quickly also improves your claim outcome, as it gives your insurer less reason to question whether secondary damage was caused by the original event or by delay.
Will a roof insurance claim affect my premium?
Making a claim can affect your renewal premium, particularly for storm damage or falling tree claims. Before claiming, weigh the cost of repair against your policy excess and the likely impact on future premiums. For minor repairs, paying out of pocket may work out cheaper. For significant structural storm damage, making a claim is usually the right decision.
Can I choose my own roofer for an insurance claim?
Yes — you have the right to choose your own roofing contractor. Your insurer may suggest their own preferred supplier, but you are not obliged to use them. Choosing a local, experienced contractor like Derby Roofers means you get someone who knows Derbyshire properties and can advocate on your behalf during the adjuster’s visit.
Do I need to pay an excess on a roof insurance claim?
Yes — your policy excess applies to roof insurance claims just as it does to any other claim. Your excess is the amount you pay before insurance covers the remaining cost. Check your policy for both your compulsory and voluntary excess before deciding whether to claim.
What happens if my roof insurance claim is rejected?
A rejected claim can be challenged. Ask your insurer for a written explanation and the evidence they relied on. Commission an independent roof inspection from Derby Roofers. File a formal complaint with your insurer — they have 8 weeks to respond. If unresolved, escalate to the Financial Ombudsman Service (FOS) within 6 months of their final decision.
Is a leaking roof covered by buildings insurance?
A leaking roof is covered if the leak was caused by an insured event — for example, storm damage that displaced tiles or broke flashing. If the leak developed gradually due to an ageing roof, failed felt, or blocked gutters, most UK policies will not cover it. The cause of the leak is what matters, which is why a professional inspection report from day one is so important.
Who is responsible for roof repairs in a rented property?
Your landlord is responsible for the structure of the building, including the roof. Their buildings insurance covers structural damage. Your contents insurance covers your belongings. If your landlord is aware of a roof problem and has failed to fix it, and that failure has caused damage to your property, speak to a housing solicitor about your options.
Areas We Cover for Roof Insurance Claims in Derby and Derbyshire
Derby Roofers proudly serves homeowners and businesses throughout Derby city and the wider Derbyshire area. Our local teams cover:
Derby City Areas:
- Derby City Centre (DE1)
- Allestree, Mackworth & Quarndon (DE22)
- Mickleover (DE3)
- Littleover & Normanton (DE23)
- Chaddesden, Oakwood & Spondon (DE21)
- Alvaston, Crewton & Osmaston (DE24)
Surrounding Derbyshire Towns & Villages:
- Belper (DE56)
- Ripley (DE5)
- Ilkeston (DE7)
- Heanor (DE75)
- Swadlincote (DE11)
- Ashbourne (DE6)
- Matlock (DE4)
- Borrowash & Draycott (DE72)
- Etwall & Hilton (DE65)
- Melbourne & Chellaston (DE73)
- Duffield & Little Eaton (DE56 / DE21)
- Breadsall & Darley Abbey (DE21 / DE22)
- Long Eaton (NG10)
- Castle Donington (DE74)
Not sure if we cover your area? Call us on 01332-529704 and we’ll be happy to help.
What the Drone Survey and Claim Report Cover
- Aerial photographs of every roof plane and elevation, date- and location-stamped for your insurer’s file
- Close-up images of the damage itself - displaced or missing tiles, cracked ridge and hip tiles, torn or lifted felt, damaged flashing around chimneys and valleys
- Ground-level or, where the angle needs it, tower and powered-access photographs of areas a drone can’t get a clear shot of, such as under overhangs or tight valley gutters
- A written report describing the damage, its likely cause, and a recommended repair scope, formatted for submission to your insurer or loss adjuster
- Measurements and a repair scope suitable for supporting a like-for-like reinstatement claim rather than a general estimate
- A copy of the report and photographs kept on file for you, whether or not you go ahead with a claim
Not Included / Costed Separately
- The repair or emergency tarping work itself, which is quoted separately once a claim is agreed
- Attending the loss adjuster’s site visit on your behalf - we can join you if asked, but it isn’t automatic
- Interior or structural surveys of ceilings, timbers, or damp - these are referred to the relevant specialist rather than covered in the roof report
- Claims for wear-and-tear rather than storm or accidental damage, since most policies exclude this regardless of how the report is written
How a Roof Claim Survey Runs, From Call to Report
- You get in touch: By phone or through the contact page, tell us the address, what happened (storm date, fallen branch, etc.), and whether you’ve already reported it to your insurer or have a claim reference.
- Free drone survey is booked: Arranged around your availability and the weather, since drone photography needs calm conditions to get usable images of every roof plane.
- Close-up check where the drone can’t see enough: For flashing, ridge pointing, or steep pitches that need a physical look rather than an aerial one, our PASMA-trained team sets up a tower, or our IPAF-trained team uses powered access, to get eyes on the detail safely.
- Written report is produced: Photographs and findings are written up into a report describing the damage, probable cause, and recommended repair scope, in a format insurers are used to receiving.
- You submit the claim: The report is yours to send to your insurer directly, or we can talk you through what it says first if you’re not sure how to present it.
- Repair quote and work, once the claim is agreed: If you decide to proceed, whether the claim is accepted in full or you’re covering part of it yourself, we quote the repair separately based on the same site visit.
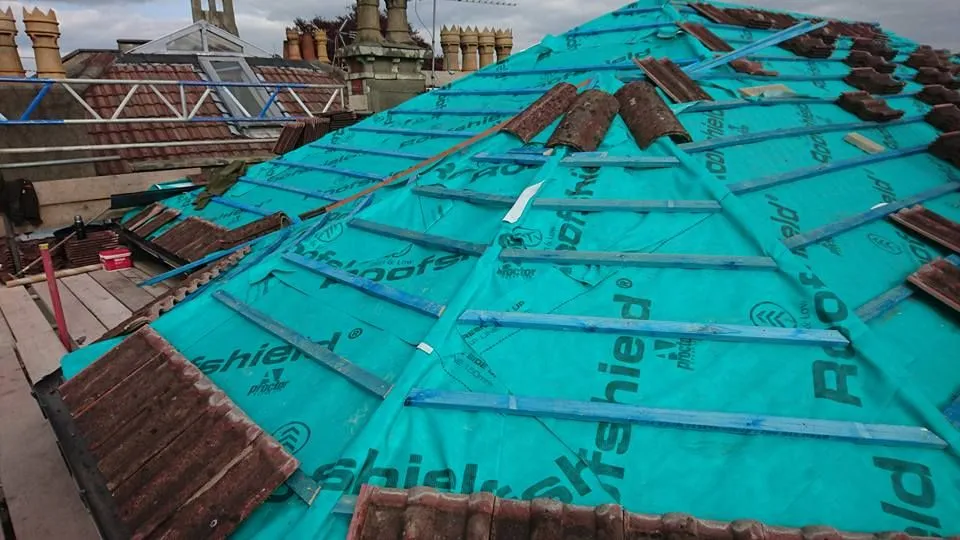
What a Roof Insurance Claim Actually Costs You
The drone survey and initial roof inspection are free, with no obligation to book any repair work afterwards. If your claim goes ahead, your policy excess still applies regardless of who carries out the inspection - that is the amount you pay before your insurer covers the rest, so it is worth weighing against the likely repair cost before deciding whether to claim at all, particularly for smaller areas of damage. For the repair work itself, pricing depends on the extent of the damage, the roof type, and whether tiles, flashing, or felt are affected, which is why a written, insurer-ready quote only follows a site visit rather than a figure given over the phone.
Doing It Alone, Using the Insurer’s Contractor, or Calling Derby Roofers
| Handling the Claim Yourself | Insurer’s Recommended Contractor | Derby Roofers | |
|---|---|---|---|
| Roof inspection | Photos from the ground only | Site visit arranged by the insurer, on their timetable | Free drone survey plus direct access inspection, booked around you |
| Written damage report | None, unless commissioned separately | Written for the insurer’s file, not handed to you | Insurer-ready written report that you keep on file |
| Adjuster visit | You attend alone | Not typically offered | We can attend with you and answer technical questions on site |
| Choice of contractor | N/A | Fixed to the insurer’s panel | Your choice of independent local contractor |
| Access to hard-to-reach areas | Limited to what you can see safely | Depends on the contractor assigned | IPAF and PASMA certified team for powered access and tower work where needed |
Roof Evidence From Chaddesden to Chellaston, Not Just From the Air
Insurers query claims most often over the damage they can’t see documented clearly - flashing tucked under a chimney stack, ridge pointing, or a pitch too steep to photograph safely from a ladder. A drone survey alone doesn’t always close that gap, which is why we go beyond it on claims across Derby’s older housing stock in Normanton and the terraces off Osmaston Road, the 1930s semis in Allestree and Mickleover, and the newer estates going up around Chellaston and Boulton Moor. Getting a proper look at those areas means working safely at height, using towers or powered platforms rather than staying on the ground, which is where the PASMA training for tower work and IPAF training for powered access held by the team members carrying out these inspections comes in. The result is a report that covers what a camera in the air can show and what it can’t, which is usually the difference between a claim an insurer accepts on first submission and one that gets sent back with questions.
Ready to Get Your Roof Inspected and Your Claim Started?
Storm damage doesn’t wait — and neither should you. The sooner you get a professional inspection and a written damage report, the stronger your insurance claim will be.
At Derby Roofers, we have supported homeowners across Derby, Derbyshire and the surrounding areas for over 20 years. We know which evidence insurers look for, we know how to document damage correctly, and we know how to be the roofing partner you need throughout the claims process.
Here is what you get when you call us:
Don’t let a rejected claim or a missed deadline cost you thousands.
📞 Call Derby Roofers now on 01332-529704 📧 Email: [email protected] 🌐 Or use our online contact form at derbyroofers.co.uk/contact-derby-roofers
We serve Derby and the whole of Derbyshire — from Allestree and Mickleover to Long Eaton, Belper, Ripley, Matlock and beyond. Call today and let us help you get your roof — and your claim — back on track.
- ✅ FREE drone survey — safe, detailed, and date-stamped
- ✅ Professional written damage report for your insurer
- ✅ Detailed repair quote that meets insurer requirements
- ✅ Roofer attendance at your adjuster visit — at your request
- ✅ 24-hour availability — we answer the phone
- ✅ Over 20 years of experience across all roof types and materials
- ✅ All materials BBA approved — 10-year guarantee on our work
“Very friendly and professional. They delivered my job on time and at a good price.”
DERBY ROOFERS - That is what we aim to hear from customers all the time.
Get a Free Quote
🔒 Your details are safe with us. No spam, ever.